By Micheal Eze | Critical Frontiers

Ghana's GoldBod Experiment: Formalisation Must Compete With the Market

Ghana's attempt to formalise its artisanal and small-scale gold trade is entering a more difficult phase. The question is no longer simply whether the state can bring more gold into official channels. It is whether those channels can remain commercially attractive to the people who supply the gold and sufficiently predictable for those who provide the capital.

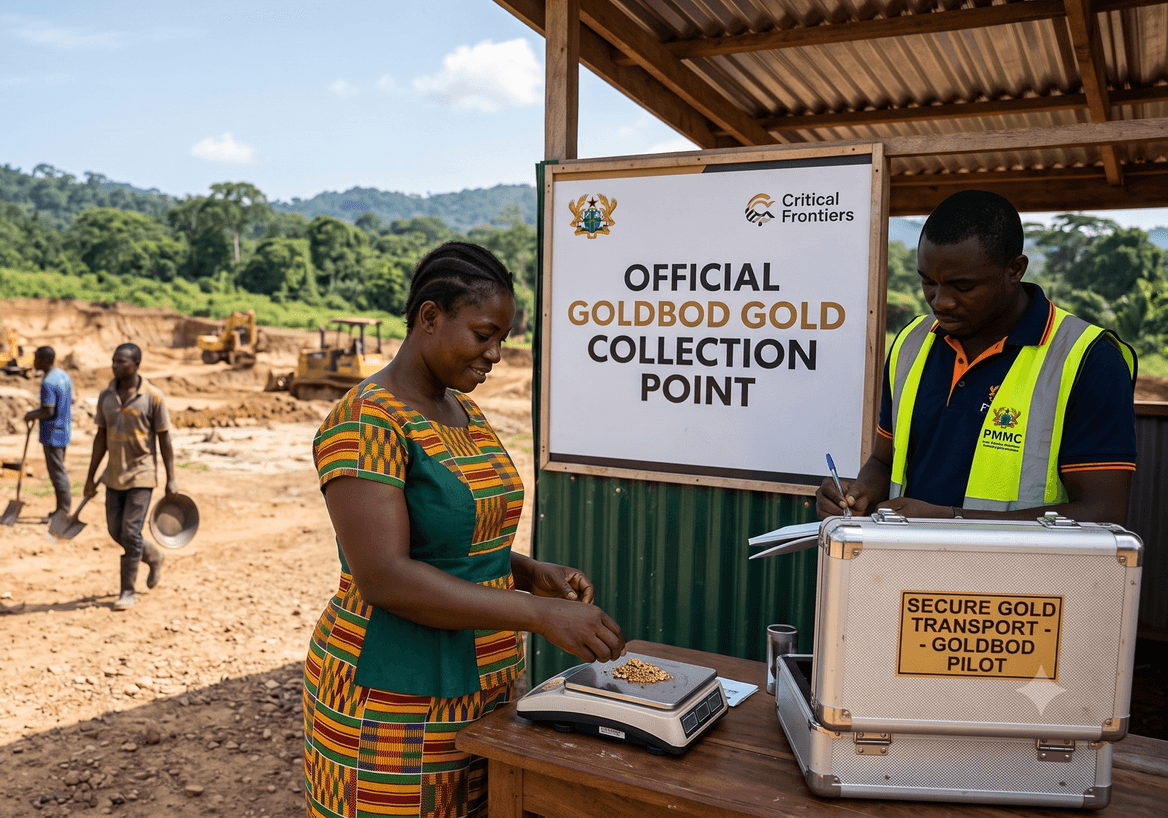
GoldBod has already shown the scale of change taking place in the formal market. Recorded artisanal and small-scale mining (ASM) gold exports increased from 63.6 tonnes in 2024 to 103 tonnes in 2025. GoldBod attributes much of that increase to gold previously lost through informal and smuggling channels entering the formal system. Those numbers matter, but they tell us how much gold has entered the formal system, not whether the conditions that brought it there can keep it there. Formalisation becomes durable when participating in the formal market makes economic sense.

The economics beneath formalisation

On August 24, Reuters reported that some GoldBod-funded buyers had gone for up to three weeks without expected advance funding, forcing some operators to suspend purchases or borrow to continue trading. GoldBod rejected suggestions of a funding shortfall, maintaining that its operations remain fully funded and that financing is now subject to creditworthiness, security and risk assessments.

Two days later, GoldBod introduced another significant requirement. From September 1, self-financing aggregators must refine artisanal gold doré in Ghana before export. Refining must take place at an approved or designated refinery, with the associated costs borne by the aggregator or approved offtaker. The policy rationale is understandable. Domestic refining can increase local value addition, while stronger financing controls can reduce financial exposure within the gold-purchasing system. But every additional requirement enters somebody's calculation of whether formal participation remains worthwhile.

Transactional lawyer Amanda Akuokor Clinton recently made this point in discussing Ghana's formalisation programme. Miners and aggregators respond to margins, payment conditions, financing, compliance costs and the availability of alternative buyers. Formalisation, therefore, has to be commercially viable for the actors it seeks to bring into the system. Regulation establishes the rules; economic incentives shape whether market participants remain within those rules or seek alternatives. That distinction changes the question policymakers should be asking. Enforcement can determine where transactions are legally permitted to occur. It cannot by itself determine where market participants find it most advantageous to transact.

Formalisation enters an existing market

Informal markets are easily misunderstood as institutional vacuums waiting for regulation. In reality, they frequently have established buyers, financing relationships, information networks and mechanisms of trust. Participants know who buys, what competitors pay and where transactions settle faster.

The formal institution therefore enters a functioning market, even if much of that activity sits outside the regulatory structure. GoldBod appears conscious of this competitive pressure. Its July pricing reforms adopted London Bullion Market Association benchmarks as the reference for official local purchase prices, while its wider programme has emphasised traceability, financing and access to compliant markets.

Yet the calculation facing a miner or aggregator remains straightforward: what is the return from selling through the formal channel relative to the available alternatives? Each additional compliance cost, financing constraint or settlement delay changes that calculation. Once those costs become sufficiently large, tighter formalisation can produce the opposite of its intended effect by increasing the incentive to divert supply into unofficial channels. The risk does not mean regulation should be weakened. It means the economics of compliance are themselves part of regulatory design.

GoldBod's two-sided viability problem

There is another constituency whose incentives matter just as much.

Formalisation requires capital. Banks, institutional buyers and offtakers need enough predictability to commit substantial funds to gold transactions. Clinton has separately raised questions about transaction predictability, foreign-exchange conversion, settlement, disclosure and the concentration of commercial and regulatory functions within GoldBod. Some claims concerning particular investor transactions remain allegations requiring independent verification. The institutional problem exists independently of those claims: investors need to know how their capital moves through the system, what costs arise along the way, and what happens when a transaction does not proceed as expected.

GoldBod therefore faces what Critical Frontiers sees as a two-sided viability problem. At one end are miners and aggregators. The formal market needs to offer sufficiently competitive prices, financing and settlement conditions to keep physical gold within official channels. At the other end are banks, offtakers and institutional investors. They need transparency, transaction certainty and sufficient confidence in the institutions governing the market to continue supplying capital.

Weakness at either end can undermine the system. Unfavourable terms for suppliers create incentives for gold to move elsewhere. Excessive uncertainty for capital providers makes financing more expensive, more conditional or simply unavailable. The two problems can also feed each other. Constrained financing can weaken formal buyers' ability to compete for gold. Lost supply can, in turn, make financing the formal market less attractive.

That feedback loop deserves as much attention as enforcement.

From compulsory to self-sustaining formalisation

Ghana's gold reforms should ultimately be judged by a harder standard than GoldBod's ability to centralise the trade. The more consequential test is whether the formal market becomes attractive enough that participants increasingly choose it because participation makes commercial sense.

There is a difference between compulsory formalisation and self-sustaining formalisation. Compulsory formalisation relies heavily on licensing restrictions, enforcement and control over market access. Self-sustaining formalisation still needs those institutions, but reinforces them with prices, financing conditions, settlement systems and transaction costs that make circumvention progressively less attractive.

The sharp increase in recorded ASM exports suggests that Ghana has already succeeded in drawing substantial gold into official channels. The next test is harder: keeping it there as financing arrangements change, compliance requirements increase, and market participants continue comparing the formal system against their alternatives. The lesson extends beyond Ghana's gold sector. Across African economies, governments routinely seek to formalise markets whose informal institutions existed long before the regulatory framework reached them. Regulation can change the legal boundaries of those markets. Lasting formalisation requires something more.

The formal institution must offer a better economic proposition than the institutional arrangement it seeks to replace.

Micheal Eze is the founder and principal analyst at Critical Frontiers, a political-economy research and advisory practice focused on institutional risk, informal markets and decision-making in West Africa. His work examines how formal rules, political incentives and market behaviour shape policy and commercial outcomes across the region.

Privacy policy | Terms of use | Cookies